 how-to
How to Stop Impulsive Spending with ADHD: 6 Steps
Table of Contents
- Why ADHD Brains Struggle With Impulsive Spending
- ADHD Spending Triggers to Recognize Before They Cost You
- Step 1: Build a Spending Plan That Fits Your ADHD Brain
- Step 2: Add Purchase Friction Before You Click Buy
- How to Stop Online Shopping with ADHD in a One-Click World
- Impulse Spending Coping Strategies for Tough Moments
- ADHD Budgeting Tips That Survive a Bad Week
- Track Progress, Handle Setbacks, and Know When to Get Help
- Frequently Asked Questions
Last Updated: October 18, 2026
Why ADHD Brains Struggle With Impulsive Spending
Impulsive spending with ADHD is not a character flaw or a willpower problem. It is a predictable result of how the ADHD brain handles reward, time, and inhibition.
Here is the short version. ADHD affects executive function, the set of mental skills that help you plan, pause, and follow through (ncbi.nlm.nih.gov). When the "pause" button is unreliable, a want becomes a purchase fast.
Executive Function and the Impulse Gap
The gap between wanting something and buying it is where impulse control lives. In ADHD, that gap is often very short. A sale email arrives, the brain lights up, and the card is out before the thinking part catches up.
This is why lectures and shame do not work. You cannot out-willpower a brain that processes rewards differently. You can, however, add steps between the urge and the checkout. More on that in Step 2.
The Self-Care vs. Self-Sabotage Loop
Many ADHD spenders buy things to feel better. A rough day leads to a treat. The treat feels good for an hour. Then the credit card statement arrives and the shame starts, which leads to more comfort buying.
That is the overspending cycle, and it runs on emotion, not logic. The goal is not to ban self-care. It is to separate real self-care from the purchases that quietly sabotage your goals.
ADHD Spending Triggers to Recognize Before They Cost You
Most overspending happens on autopilot. Learning your personal triggers turns a blind spot into a warning sign you can act on. The four most common categories of ADHD spending triggers are emotional, environmental, social, and digital.
Start by tracking for one week. Write down what you bought, what you felt, and where you were. Patterns appear fast.
Emotional Triggers: Stress, Boredom, and Low Mood
Stress, boredom, and low mood are the big three. Each one pushes the brain toward a quick dopamine hit, and shopping delivers exactly that.
Watch for these signals:
- You open a shopping app when you feel restless, not when you need something
- Browsing starts right after a stressful email or meeting
- You buy "little treats" to get through a flat afternoon
Naming the feeling before you buy is a skill. It gets easier with a simple tracker. Our ADHD Life Planner for Adults includes pages for exactly this kind of daily check-in.
Step 1: Build a Spending Plan That Fits Your ADHD Brain
A spending plan is a simple map of where your money goes, built to survive a bad week. Forget the twelve-category spreadsheet that assumes you will remember to open it. ADHD-friendly budgets are short, visual, and forgiving, and they work best when you build them in a specific order rather than all at once.
The four-part build (do it in this sequence)
- List fixed obligations first. Rent, utilities, insurance, minimum debt payments, subscriptions you actually use. These are non-negotiable and should be automated the same day you list them. Automation removes the executive-function load of remembering.
- Set a single flexible-spending number. Instead of tracking ten categories, pick one weekly number for everything discretionary, groceries beyond staples, coffee, fun, clothes. One number is easier to remember and harder to rationalize around.
- Name one goal with a deadline. "Save for a trip by summer" beats "save more." A deadline gives the ADHD brain a concrete target, and a visible progress bar (paper or app) supplies the small dopamine hit that keeps the plan alive.
- Add a buffer line. A small "oops" amount set aside for the slip-ups that will happen. The buffer is not permission to overspend; it is the thing that keeps one bad week from collapsing the whole plan.
Match the plan to how your ADHD actually shows up
A plan that works for one person can fail for another because ADHD presentations differ. A few common patterns and the adjustment that tends to help:
- Online impulse buyer: the plan needs a weekly "shopping window" and a rule that non-essential carts sit for 48 hours before checkout. The budget category stays the same; the friction lives in the timing.
- In-store spender: carry a physical list and a set cash amount for the trip. Leaving cards at home for quick errands removes the tap-to-pay shortcut.
- Subscription creep: run a quarterly subscription audit. List every recurring charge, cancel anything you have not used in the last month, and set a calendar reminder for the next audit.
Trade-offs to expect
A simpler plan is easier to follow but less precise. A detailed plan gives better data but is more likely to be abandoned in a bad week. Most people with ADHD do better starting simple and adding detail only after the simple version has survived a month. The point is a plan you will actually use, a messy plan you check beats a perfect one you abandon.
Step 2: Add Purchase Friction Before You Click Buy
Purchase friction is any deliberate speed bump between the urge and the checkout. It works because it gives your slow-to-engage executive function time to catch up. Add friction and the impulse fades before the money leaves.
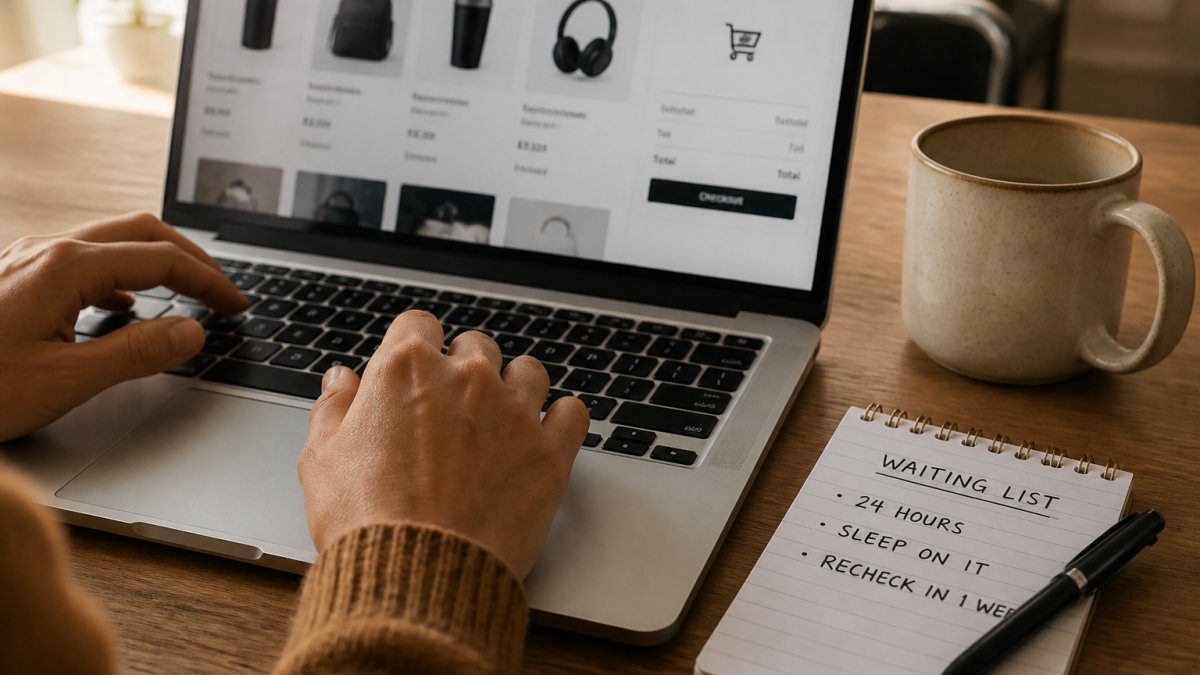
Practical friction ideas:
- Delete saved payment details so every purchase needs a card typed in
- Remove shopping apps from your phone's home screen
- Log out of shopping accounts after each visit
Each step adds a few seconds. Those seconds are where the decision actually happens.
How to Stop Online Shopping with ADHD in a One-Click World
Online shopping is engineered to remove friction, which is the exact opposite of what an ADHD brain needs. To stop online shopping with ADHD, you have to rebuild the friction the platforms stripped out.
Here is a checklist to run once and forget:
- Turn off one-click and stored-card checkout in every store account
- Unsubscribe from marketing emails and push alerts
- Move shopping apps into a hidden folder or delete them
The unsubscribe step matters more than people expect. Fewer prompts means fewer urges.
ADHD Money Guide and Workbook, Money Management for Neurodivergent Adults →
Impulse Spending Coping Strategies for Tough Moments
Coping strategies are for the moment the urge hits, not for planning ahead. The goal is to ride out the wave without spending Many people notice an urge peaks and starts to fade within minutes.
Try these impulse spending coping strategies:
- Deep breathing: four slow breaths before you touch your phone
- Movement breaks: a short walk or ten jumping jacks to reset the urge
- Physical activity: anything that gets your body moving and your mind off the cart
None of these are magic. Together they give your thinking brain a chance to weigh in.
ADHD Budgeting Tips That Survive a Bad Week
Good ADHD budgeting tips assume bad weeks will happen. The plan is not to avoid them. It is to make them less expensive.
What works in practice:
- Automate the boring parts. Set bills and savings to move on their own.
- Use a weekly money check-in, ten minutes, same day each week.
- Keep a small "oops" buffer for the slip-ups that will happen.
The spending review is where the learning happens. Look for patterns, not perfection. A short, honest review beats a detailed one you skip.
Track Progress, Handle Setbacks, and Know When to Get Help
Most advice stops at prevention. The harder, more useful work is what happens after a spending episode, and how you measure whether your systems are actually working. This section covers the three things competitors tend to skip: simple progress indicators, a recovery sequence for lapses and debt, and clear guidance on shared finances and when to bring in outside help.
Measure progress with simple indicators
Perfect months are a bad scoreboard for ADHD. Track patterns instead. A weekly ten-minute review using three measures tells you more than any single number:
- Unplanned purchases per week. Count them, do not judge them. The trend matters more than any one week.
- Spending against your flexible number. Did the week land under, on, or over the single discretionary figure from Step 1?
- Time between urge and purchase. Note roughly how long passed between wanting something and buying it. A growing gap is the clearest sign your friction systems are working.
Keep the review short and put it on the calendar. A five-minute honest review beats a detailed one you skip.
Recover from a spending episode
A lapse is data, not a verdict. The recovery sequence is short and should start the same day, not next month:
- Note the trigger without shaming yourself. What feeling, place, or prompt came right before the purchase?
- Return what you can and cancel what you can. Unopened items, duplicate subscriptions, and impulse add-ons are often recoverable within the return window.
- Adjust the system so the same trigger is harder to hit. If a sale email set it off, unsubscribe. If a late-night browse set it off, add a phone cutoff.
- Restart the routine the next day. The goal is a short dip, not a lost month.
If a purchase created a balance you cannot clear in one cycle, treat the debt as its own small project: list the balance, the minimum payment, and a payoff target, and put the minimum on autopay so a bad week cannot cause a missed payment. A nonprofit credit counselor can help you build a payoff plan if the numbers feel unmanageable.
Shared finances and supportive accountability
When spending affects a household, accountability works only with consent and clear boundaries. A few ground rules that keep support from turning into shame:
- Agree on what gets shared. Decide together which accounts and categories are visible to both people, and which stay private.
- Set a check-in, not a surveillance. A short weekly money conversation beats monitoring each other's transactions.
- Use non-shaming language. "I noticed the fun category ran over, want to adjust it together?" lands very differently from "you overspent again."
Know when to get help
Most overspending is manageable with systems and support. Bring in outside help when spending feels out of control despite your systems, when debt is growing faster than you can pay it down, or when money stress is affecting sleep, mood, or relationships. A therapist trained in cognitive behavioral therapy (CBT) can help with the emotional side of spending, and a nonprofit credit counselor can help with debt.
Our ADHD Money Guide and Workbook walks through impulse spending and money management step by step, and our ADHD Budget Planner Printable gives you the paycheck and bill tracking pages to put it into practice. Both are fillable PDFs you can use on a tablet or print at home, and you own them for good.
Frequently Asked Questions
How can adults with ADHD stop impulsive spending?
Start with friction and structure rather than willpower. Remove saved payment details, delete shopping apps, and set a waiting period before any unplanned purchase. Build a simple spending plan with a few broad categories instead of a detailed budget you will abandon. Identify your ADHD spending triggers, such as stress or boredom, and write down a replacement action for each one. Track purchases weekly so patterns become visible, and treat a slip as information rather than failure. FocusedAndFiled's ADHD Money Guide and Workbook walks through these steps in a printable format.
What are the most common ADHD spending triggers?
Stress, boredom, and low mood are the big three. Many people also spend in response to rejection, excitement, or transitions like finishing a task or arriving home. Online shopping adds its own triggers: flash sales, push notifications, and saved payment details that remove the pause between wanting and buying. Once you name your specific triggers, you can plan a response in advance. A short list of two or three triggers and one alternative action each is often enough to interrupt the cycle before checkout.
How do I pause before making an unplanned purchase?
Use a written cooling-off period. For anything outside your spending plan, add it to a waiting list with the date and the amount, then revisit it after a set time you choose in advance, such as 48 hours. Remove saved cards and app logins so buying takes effort. If the urge is strong, do a short movement break or a few slow breaths first. The goal is not to never buy; it is to put enough time between the urge and the purchase that your thinking brain gets a turn.
What should I do after an impulsive purchase?
Do not spiral. First, check the return window and send back anything you do not genuinely need. Second, write down what happened right before the purchase: the feeling, the trigger, and the time of day. Third, adjust one point of friction so the same situation is harder next time. If the purchase created a bill you cannot cover, contact the company about a payment plan before the due date. A single spending episode is a data point, not proof that you cannot manage money.
The hardest part of managing money with ADHD is not knowing what to do. It is keeping the system going when life gets loud. FocusedAndFiled builds ADHD-friendly planners and trackers that make the routine easier to keep, with fillable PDFs, printable pages you can reprint as often as you need, and layouts designed to reduce overwhelm instead of adding to it. Get started with FocusedAndFiled and give your money plan a structure that fits how your brain actually works.